


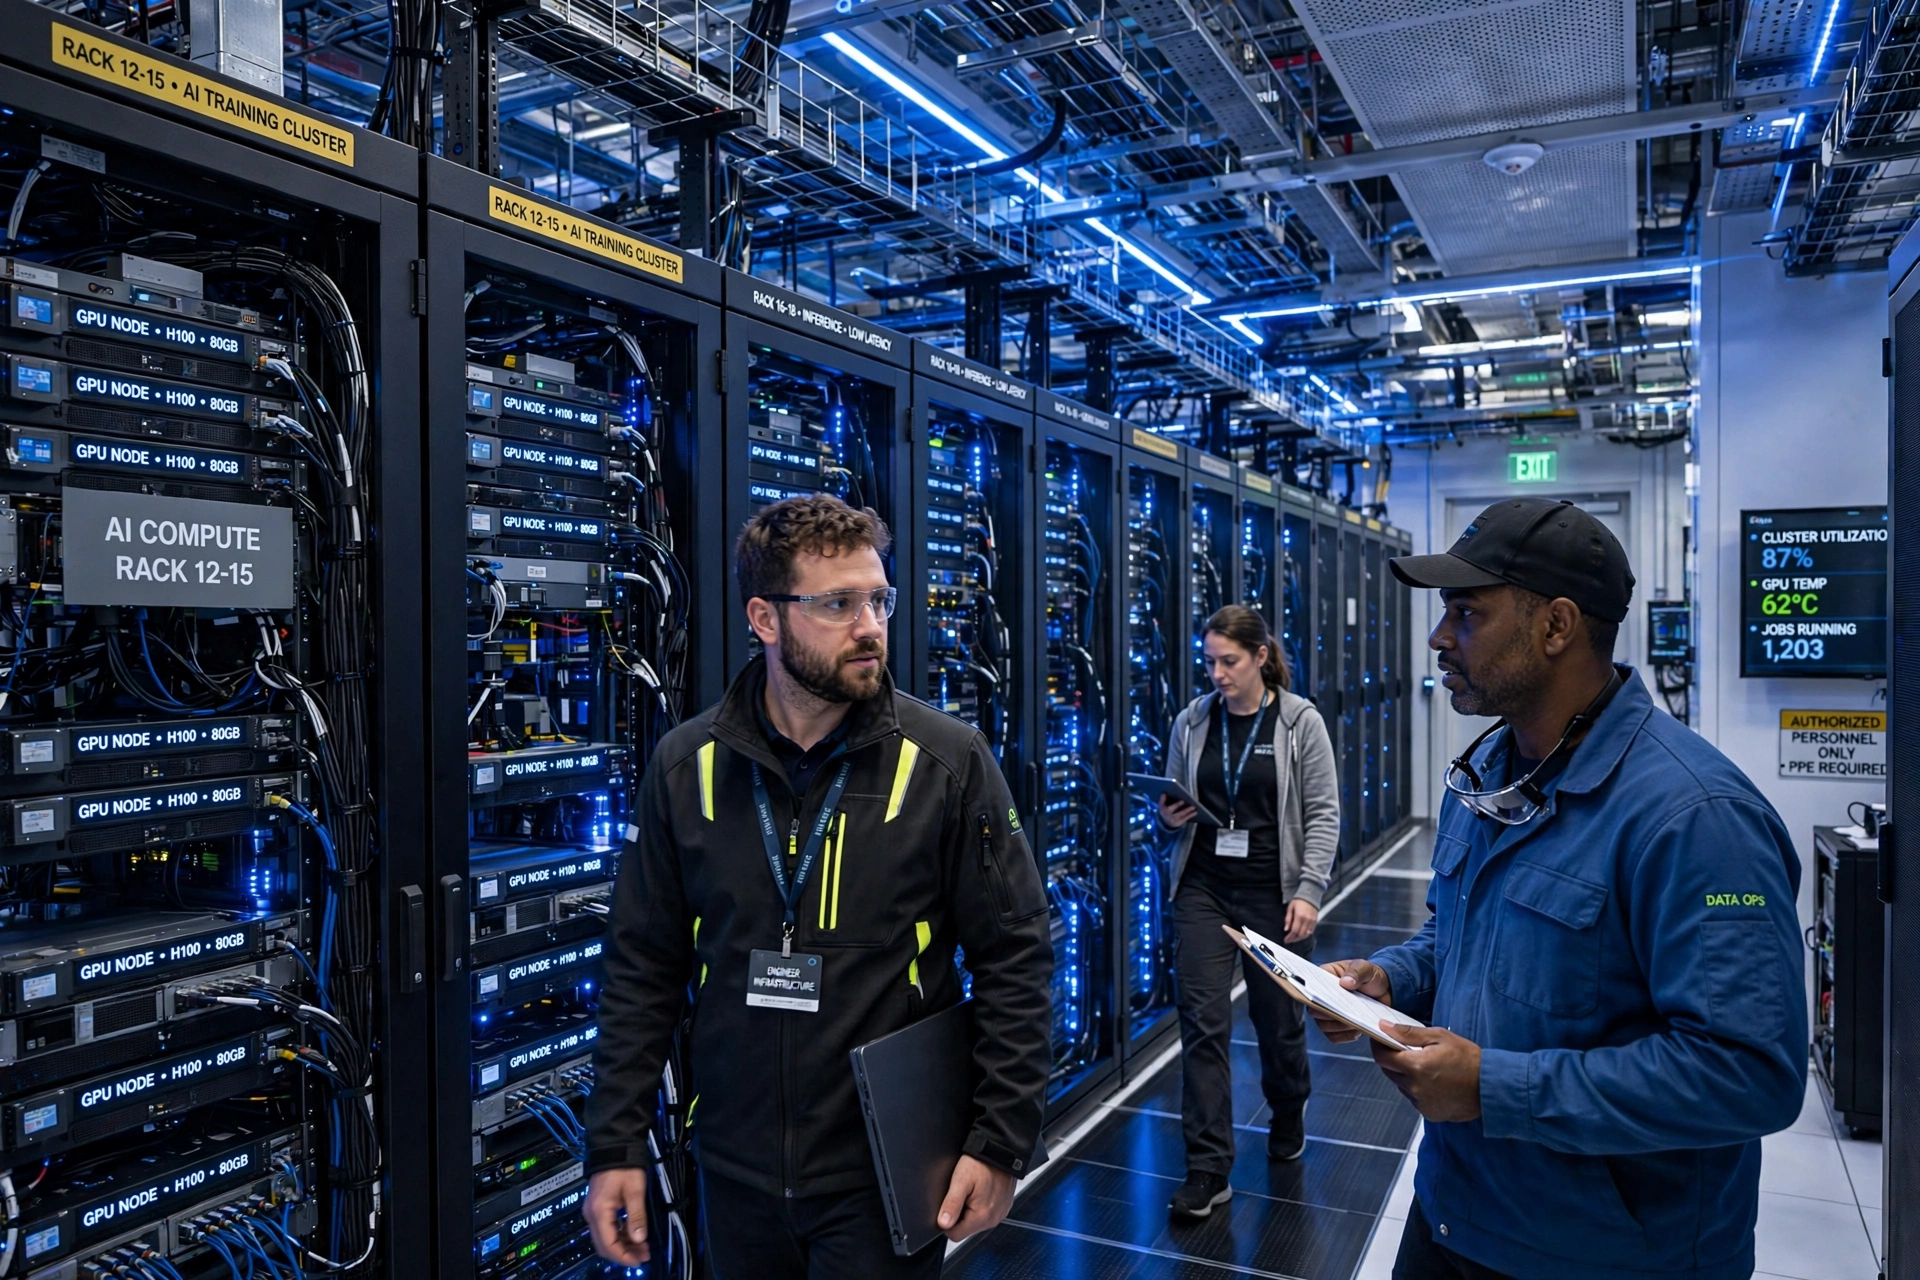
The race to build artificial intelligence has turned into a race to build buildings — vast, power-hungry data centers filled with thousands of specialised chips. This week, fresh forecasts about how much that building boom will cost have sharpened a question investors have been asking for months: does the spending still add up? The numbers are now so large that analysts say paying for AI infrastructure at the current pace would require revenues the industry has not yet shown it can generate.
A Building Boom Unlike Anything Tech Has Seen
For decades, the technology industry grew on relatively light foundations. Software companies needed offices, laptops and rented cloud space. AI has changed that completely. Training and running modern models requires data centers that can cost billions of dollars each, draw as much electricity as a small city, and take years to plan, permit and connect to the grid.
Hyperscalers and chipmakers have committed to spending at a pace that rivals national infrastructure programmes. Each new generation of AI chips is faster, but also more power-hungry, which means the buildings, cooling systems and substations around them must grow too. As we noted in our look at why on-device AI is becoming the smartphone feature that matters, part of the industry’s answer is to push more work onto devices themselves — but the cloud build-out shows no sign of slowing.
Where the Money Actually Goes
It helps to break the bill into parts. The largest share goes on accelerators — the graphics and custom AI chips that do the training. Next comes networking: connecting tens of thousands of chips so they can work as one machine requires cabling and switches that are themselves a major market. Then there is power and cooling, land, construction, and the long contracts needed to secure electricity years in advance.
The International Energy Agency has become one of the most closely watched voices in this debate. Its research on energy and AI tracks how data center electricity demand is growing and what it means for grids, emissions and energy security. When an energy agency becomes required reading for tech investors, it tells you how physical this supposedly digital revolution has become.
Why Investors Are Asking Harder Questions
Spending is not a problem by itself. Companies routinely invest ahead of demand, and the firms building AI infrastructure are among the most profitable in history. The concern is the gap between the investment curve and the revenue curve. Enterprise customers are adopting AI tools, but many are still experimenting, piloting and measuring — not yet paying sums that match the infrastructure being built for them.
That gap creates three risks. First, depreciation: chips bought today may be superseded within a few years, long before the buildings around them are paid off. Second, utilisation: a data center built for expected demand that arrives late is an expensive, half-empty warehouse. Third, circular deals — where chipmakers invest in AI companies that then buy their chips — can make demand look stronger than end-customer spending really is.
The Energy Constraint Is Real
Even if the money were unlimited, the electricity is not. In several regions, grid connection queues now stretch for years. That is why builders are signing nuclear power deals, funding new gas plants, experimenting with geothermal energy, and in some cases generating power on site. Local communities, meanwhile, are asking what they get in return for hosting facilities that employ relatively few people once built but place heavy demands on water and power networks.
For businesses planning their own AI strategies — a theme we explored in how professional firms are rethinking strategy and technology — the practical lesson is that AI capacity will not be infinite or uniformly cheap. Pricing for premium models and priority access is likely to reflect the true cost of the infrastructure behind them.
What Changes Next
None of this means the build-out stops. More likely, it becomes more disciplined. Expect tougher questions in earnings calls about returns on capital, more emphasis on efficient smaller models, and growing interest in techniques that squeeze more work from each chip. Efficiency, in other words, becomes a competitive weapon rather than an engineering nicety.
Expect, too, a clearer split between training and everyday use. Training the biggest models will stay concentrated in giant facilities owned by a handful of players. Everyday AI — the kind embedded in phones, laptops, cars and workplace software — will increasingly run closer to the user, where it is cheaper and faster.
The Bottom Line
The AI era is being built with concrete, copper and megawatts, not just code. The spending boom has created real assets and real capability, but the math now has to prove itself: revenues, efficiency and energy supply must catch up with ambition. The companies that manage that balance — building enough, but not blindly — will define the next phase of the industry. For everyone watching from the outside, the smartest question is no longer who is spending the most, but who is spending it best.
